We Tested:
Here’s a question worth sitting with: What happens when the most reliable rocket in history stops taking your calls?
That’s not a thought experiment. It’s the reality satellite companies faced in late 2026. SpaceX—the company that launched 82% of private-sector rockets and built the Falcon 9 into the workhorse of the modern space age—stopped taking new rideshare reservations beyond 2028 and began winding down Falcon 9 operations in favor of Starship and its own Starlink constellation. The company that made access to space feel routine was, quite deliberately, making it scarce again.
At the same moment, global space investment hit a record. Space Capital reported $92.5 billion invested through Q3 2026, already surpassing 2025’s full-year total and on track to cross $100 billion for the first time. The World Economic Forum projects a $1.8 trillion space market by 2035.
So space in 2026 is not one story. It’s a collision of stories: a funding boom and a launch bottleneck, a triumphant lunar flyby and a stalled Mars dream, a telescope rewriting cosmology and a debris field threatening to close the door behind us. This article is your field guide to that collision—not as a list of headlines, but as a coherent picture of where humanity’s relationship with space actually stands.
Background: How We Got to the Launch-Shortage Paradox
For roughly a decade, the commercial space economy operated on a single, comfortable assumption: if you built a satellite, a Falcon 9 would be there to launch it. SpaceX’s reusable rocket model drove launch costs down dramatically, normalized rideshare missions, and made space accessible to startups, universities, and smaller nations that had never before dreamed of owning orbital assets.
That assumption was a foundation, not a law of physics. And in 2026, it expired.
The shift is structural, not accidental. SpaceX’s priorities have moved up the value chain. Starship—the fully reusable, super-heavy-lift vehicle—reached orbit in September 2026, carrying next-generation Starlink satellites for SpaceX itself. Falcon 9’s retirement is part of a deliberate transition toward a vertically integrated future in which SpaceX is less a launch service provider and more an infrastructure company: connectivity, Earth observation, and eventually interplanetary transport.
The result is a gap. Launch capacity that once served the entire market is being redirected inward. And into that gap has poured capital, competition, and a new cast of characters.
The Main Storylines Defining Space in 2026
1. The Launch Shortage Is Real—and It’s Reshaping the Industry
The numbers tell a stark story. Pure Launch—the segment of the market dedicated to rocket launch services—raised a record $7.8 billion in 2026. Stoke Space raised a $1 billion Series E for its reusable Nova rocket. Blue Origin, which had operated for 26 years without outside capital, took external investment for the first time and told CNBC the round was oversubscribed.
Why the frenzy? Because scarcity creates opportunity. As Space Capital CEO Chad Anderson put it, the launch shortage is “the best thing to happen to the rocket industry in ten years”—it forces investors and customers to fund and use backup providers rather than defaulting to SpaceX.
The geographic diversification is striking. In a single quarter, China netted a Long March 10B booster at sea and landed a Zhuque-3 rocket; India’s Skyroot flew the country’s first private rocket to orbit; and Isar Aerospace became the first commercial company to reach orbit from Western European soil. Europe raised $6.3 billion in a record quarter, representing 28% of global investment—its highest share since 2019.
The deeper insight: The launch shortage is not a failure of the space economy. It’s a maturation symptom. When access to orbit becomes the bottleneck, capital flows toward solving that bottleneck. The companies that solve it will not remain pure launch providers for long—they’ll move into the more lucrative markets that reliable access unlocks.
2. Artemis II: A Lunar Flyby That Matters More Than It Seems
On April 3, 2026, four astronauts—Reid Wiseman, Victor Glover, Christina Koch, and Jeremy Hansen—fired their Orion capsule’s engine and left Earth orbit for the Moon. It was the first crewed lunar flyby in more than half a century, since Apollo 17 in 1972.
The mission was not without its wrinkles. A communications issue and a malfunctioning toilet were among the minor problems the crew troubleshot. But the translunar injection burn—the five-minute-and-49-second maneuver that committed the spacecraft to its lunar trajectory—executed successfully. The 10-day Artemis II mission is designed to pave the way for a Moon landing in 2028.
Why this matters beyond the symbolism: Artemis is not just a nostalgia tour. It is the testbed for deep-space human operations—life support, radiation exposure, navigation, and the integration of commercial hardware into government missions. NASA has already named the crew for Artemis III, and while the agency has faced schedule slips and cost overruns, the Artemis II flight demonstrated that the architecture works.
The nuance most coverage misses: Artemis II is a bridge mission. Its success is not measured by what it achieves in 10 days, but by what it de-risks for the landings, habitats, and commercial partnerships that follow.
3. The Mars Dream Slips—and That’s Not Necessarily Bad
Elon Musk had promised a Starship mission to Mars by the end of 2026, timed to a favorable Earth-Mars alignment. That deadline has quietly moved. By early 2026, Musk was speaking of uncrewed Mars flights in “five to seven years,” with crewed missions following later—a timeline slip of roughly a decade.
The reasons are practical. Starship’s development has been rapid but not instantaneous. Orbital refueling and cryogenic propellant storage—technologies NASA’s own GAO flagged as lagging—remain unresolved. And SpaceX’s attention has been pulled toward the Moon (via Artemis), Starlink, and the commercial launch market that funds everything else.
The original angle: The Mars delay is not a failure of ambition. It’s a recalibration of sequencing. The infrastructure required for Mars—reusable heavy-lift, orbital refueling, life support at scale—is the same infrastructure required for a sustainable lunar economy and commercial space stations. Building that infrastructure slowly is less exciting than a 2026 Mars flag-planting, but it’s more likely to produce a durable human presence beyond Earth.
4. Space Tourism: Growth, Pauses, and the Experience Gap
Space tourism in 2026 is a study in contrasts. Virgin Galactic is preparing to resume commercial flights with its Delta-class spaceplane in late 2026, targeting six passengers per flight. Axiom Space has flown four private astronaut missions to the ISS and plans Ax-5 for early 2027. SpaceX’s Crew Dragon continues to carry private crews on orbital missions, including the Polaris Dawn flight that reached 1,400 km—the highest human altitude since Apollo.
But Blue Origin, one of the most visible names in suborbital tourism, announced in January 2026 that it would pause New Shepard tourism flights for at least two years to redirect resources toward its Artemis lunar lander program. The pause is a reminder that space tourism is still a capital-intensive, strategically fragile business—not yet a self-sustaining industry.
The price spectrum remains enormous: roughly $200,000–$450,000 for a suborbital hop, $50–$100 million or more for an orbital stay. The market is estimated at $1.3–1.9 billion as of 2025—real, but small relative to launch and satellite services.
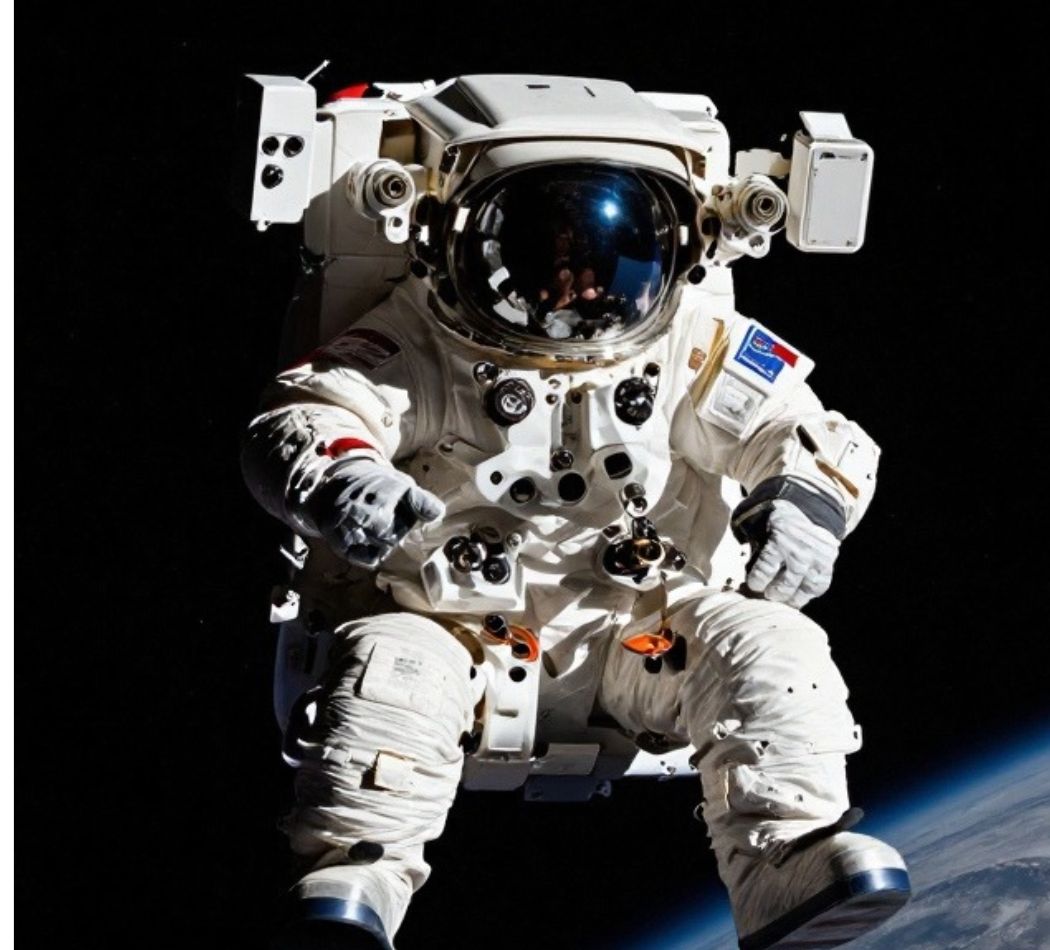
The overlooked psychological dimension: Much of the value of space tourism is not the altitude but the overview effect—the profound cognitive and emotional shift reported by astronauts when they see Earth against the blackness of space. If tourism can democratize that experience, even partially, its cultural impact may exceed its economic footprint. But at current prices, that democratization remains a distant promise.
5. JWST and the “Black Hole Star”: Cosmology Gets Weirder
While the business pages focused on launch economics, the James Webb Space Telescope quietly rewrote astronomy again. In 2026, an international team using JWST discovered a new class of object: a “black hole star”—a supermassive black hole enshrouded in gas, dating from close to the beginning of the universe, roughly 660 million years after the Big Bang.
Webb also detected dust and water surviving surprisingly close to Sagittarius A*, the Milky Way’s central supermassive black hole—material that should not, by conventional models, be able to form and persist in such an extreme radiation environment. And it found water, carbon dioxide, and possibly hydrogen sulfide in the atmosphere of exoplanet HAT-P-1 b.
Why this is not just “science trivia”: JWST is testing the boundaries of astrophysical models. The existence of “black hole stars” and resilient dust near supermassive black holes suggests that the early universe was more complex—and more efficient at producing the building blocks of stars and planets—than we assumed. That has implications for how we understand planet formation, the distribution of habitable environments, and ultimately the question of life beyond Earth.
6. Space Debris: The Quiet Crisis
The Kessler syndrome—a runaway cascade of orbital collisions that could render low Earth orbit unusable—has been a theoretical threat for decades. In 2026, it is becoming an operational reality. The European Space Agency’s 2026 Space Environment Report concluded that prevention alone is no longer enough; active debris removal must become part of the solution, and soon. The report notes that collisions are now causing new debris, and the Kessler syndrome’s runaway effect is becoming visible earlier than projected.
This is the dark side of the launch boom. More satellites, more congestion, more collision risk. The companies and governments building the space economy are also, collectively, undermining its long-term sustainability. The solutions—space traffic management, end-of-life disposal, and active removal—are technically feasible but economically and politically difficult. The entities that benefit most from orbit are not always the ones bearing the cost of keeping it clean.
7. China’s Tiangong: The Other Space Station
While the ISS nears the end of its operational life, China’s Tiangong space station has become a fully operational research platform, orbiting Earth 16 times a day and hosting a rotating crew. In 2026, China launched the Shenzhou-23 crew and moved closer to hosting its first foreign astronaut, a Pakistani payload specialist.
Tiangong represents a parallel track in human spaceflight: a Chinese-led platform that is explicitly open to international cooperation, particularly among nations that may not have access to the ISS or to Western commercial stations. The geopolitical implications are significant. If Tiangong becomes the primary destination for astronauts from emerging space nations, it could reshape the diplomatic landscape of space—not through confrontation, but through alternative infrastructure.
Practical Tips: How to Engage with Space in 2026 (Without a Rocket)
You don’t need to be an astronaut, an engineer, or a billionaire to participate in the space economy. Here’s how to make space practical in your own life and work.
-
Use space data, not just space imagery. Satellite-derived insights are already embedded in agriculture, logistics, insurance, and climate monitoring. If your industry depends on weather, geography, or remote assets, there is likely a space-data product that can improve your decisions. Start by identifying one operational uncertainty that satellite data could reduce.
-
Watch the launch-shortage opportunity. If you are an investor or founder, the launch bottleneck is a signal. Companies that provide alternative access to orbit—or that reduce the need for launch through in-space manufacturing or servicing—are positioned for structural growth.
-
Follow the spinoffs. NASA’s Spinoff program has documented over 2,400 technologies adapted for terrestrial use, from implantable heart monitors to search-and-rescue beacons. Space innovation is not just about going up; it’s about coming back down in useful forms.
-
Treat debris as a business risk. If your company relies on satellites, the Kessler risk is not an abstract environmental issue. It is a supply-chain and continuity risk. Demand transparency from launch providers on disposal practices, and factor orbital congestion into long-term asset planning.
-
Experience the overview effect vicariously—and advocate for it. Space documentaries, VR experiences, and astronaut memoirs can convey some of the cognitive shift of seeing Earth from orbit. But the more important action is to support policies and programs that broaden access to that perspective, because the overview effect is not just a personal epiphany—it is a potential driver of wiser planetary stewardship.
Common Mistakes and Challenges (Plus Solutions)
Mistake #1: Assuming the launch shortage means space is “slowing down.”
It doesn’t. It means the market is reallocating. The solution is to distinguish between capacity and demand. Demand for orbit is higher than ever; the supply of reliable rides is constrained. That is a transitional problem, not a terminal one.
Mistake #2: Treating Artemis and Starship as the whole story.
Human spaceflight gets the headlines, but the majority of the space economy is in satellites, connectivity, Earth observation, and defense. Ignoring the infrastructure layer is like covering the internet by only writing about astronaut launches.
Mistake #3: Dismissing space tourism as frivolous.
It is easy to mock millionaire joyrides. But tourism is a revenue stream that subsidizes vehicle development, drives safety improvements, and normalizes the idea of civilian spaceflight. The challenge is ensuring it does not become the only model of human access.
Mistake #4: Underestimating debris.
The Kessler syndrome is not a science-fiction scenario. It is a measurable trend. The solution is not to stop launching; it is to launch responsibly—with mandatory disposal, traffic coordination, and investment in removal technologies.
Mistake #5: Expecting linear progress.
Space development is punctuated by delays, failures, and strategic pivots. The Mars slip is an example. The Blue Origin tourism pause is another. The mistake is to read every delay as a verdict on the industry’s future. The correct response is to track the underlying infrastructure—launch cadence, cost curves, refueling capability—rather than the headline promises.
Pros, Cons, and a Balanced Analysis
| Pros of the 2026 Space Landscape | Cons and Risks |
|---|---|
| Record investment ($100B+) signals long-term confidence | Launch shortage creates bottlenecks for smaller operators |
| Diversification of launch providers reduces single-vendor dependence | Debris and orbital congestion threaten long-term sustainability |
| Artemis II restores human lunar capability and de-risks future landings | Mars timelines have slipped significantly, testing public patience |
| JWST discoveries expand scientific frontiers and challenge paradigms | Space tourism remains expensive, uneven, and vulnerable to strategic pauses |
| Space tech spinoffs deliver concrete benefits on Earth | Geopolitical competition (China’s Tiangong, U.S.-China rivalry) complicates cooperation |
The balanced take: Space in 2026 is neither a utopia nor a bubble. It is an industry in a painful but productive transition—from a government-led, launch-centric model to a commercially driven, infrastructure-oriented one. The winners will be those who solve the bottlenecks, not those who ignore them.
Future Trends and Predictions (2027–2035)
1. The launch market will not remain scarce forever. The capital flowing into Stoke, Blue Origin, Isar, and Chinese and Indian providers will eventually produce capacity. The question is when—and which providers survive the transition.
2. Commercial space stations will become the next platform war. With the ISS aging, Axiom, Voyager, and others are racing to establish commercial destinations. The model will look less like a government program and more like a real-estate and services market.
3. In-space manufacturing will move from demo to product. Fiber optics, pharmaceuticals, and novel materials benefit from microgravity. The companies that master orbital production will create entirely new supply chains.
4. Active debris removal will become a mandatory cost of doing business. Expect regulation, insurance requirements, and a new industry of orbital “tow trucks” and disposal services.
5. JWST’s successors—and competing telescopes—will intensify the cosmology revolution. The “black hole star” is likely the first of many objects that force us to revise our models of the early universe.
6. China will become a genuine alternative hub for human spaceflight. Tiangong’s international outreach is a long game. By the 2030s, the question may not be “ISS or Tiangong” but “which ecosystem does your country or company belong to?”
Conclusion: The Space Age Is Not a Spectator Sport
The most important shift in 2026 is not a single mission or a single funding record. It is the realization that space has become infrastructure—contested, capital-intensive, and deeply embedded in life on Earth. The launch shortage, the debris crisis, the Artemis flyby, and the black hole star are all symptoms of the same underlying phenomenon: humanity is building a permanent presence beyond the atmosphere, and the systems that support that presence are under strain.
The good news is that strain is a sign of use. The bad news is that use without stewardship creates fragility. The next decade of space will be defined less by spectacle than by maintenance—of orbits, of supply chains, of international norms, and of our collective sense of wonder.
Key Takeaways
-
2026 is a paradox year: record investment and a launch shortage coexist because the space economy is transitioning from launch-centric to infrastructure-centric.
-
The launch shortage is an opportunity for diversified providers and a risk for anyone dependent on a single rocket.
-
Artemis II proves the architecture works; the real test is sustaining lunar and cis-lunar operations through the 2020s.
-
Mars has slipped, but the infrastructure being built for the Moon and for commercial stations is the same infrastructure Mars will require.
-
Space tourism is growing, but unevenly; its cultural value may ultimately exceed its near-term market size.
-
JWST is rewriting cosmology with objects like the “black hole star,” reminding us that the universe is stranger than our models.
-
Space debris is the quiet crisis that could undermine everything else; active removal is no longer optional.
-
China’s Tiangong is a parallel track in human spaceflight that will shape the geopolitics of space for decades.
Frequently Asked Questions (FAQs)
Q: Is the space economy actually growing, or is it just hype?
Both. Investment is at record levels and the long-term trajectory is upward, but the sector is volatile. The launch shortage and the Mars delay are real constraints. The growth is real, but it is not linear.
Q: Why did SpaceX stop taking rideshare reservations?
SpaceX is redirecting capacity toward Starship and its own Starlink constellation. It is a strategic pivot from being a launch service provider to being an integrated infrastructure company.
Q: Did Artemis II land on the Moon?
No. Artemis II was a crewed lunar flyby—a 10-day mission that looped around the Moon and returned to Earth. The landing is planned for Artemis III, targeted for 2028.
Q: Is space tourism safe?
Commercial spaceflight has a strong safety record in recent years, but it is not risk-free. Suborbital flights are brief and highly automated; orbital missions involve longer exposure and more complex systems. Safety standards are still evolving.
Q: What is a “black hole star”?
It is a newly discovered class of object: a supermassive black hole enshrouded in dense gas, believed to exist in the early universe. JWST found evidence of one dating to roughly 660 million years after the Big Bang.
Q: Why is space debris suddenly a bigger deal?
Because the number of objects in orbit has grown dramatically, and collisions are now generating new debris. The Kessler syndrome—a runaway cascade—is no longer purely theoretical.
Q: Can regular people go to space?
Yes, but it is expensive. Suborbital flights cost hundreds of thousands of dollars; orbital stays cost tens of millions. Prices are expected to fall gradually, but widespread access remains years away.
Q: What does China’s Tiangong mean for the U.S. and other spacefaring nations?
Tiangong is a fully operational space station that is opening to international partners. It represents a genuine alternative platform for human spaceflight and could shift the diplomatic dynamics of space cooperation.
Sources
-
World Economic Forum, “3 commercial trends propelling a $1.8 trillion space market,” October 2026.
-
Space Capital, “Space IQ: Q3 2026,” October 2026.
-
Business Insider / TipRanks, “Space Sector Funding Surpasses $100 Billion as SpaceX IPO and Falcon 9 Retirement Fuel Rival Rocket Makers,” October 2026.
-
RNZ / AFP, “NASA gives Artemis astronauts green light for lunar orbit,” April 2026.
-
Orbital Radar, “Space Tourism: The definitive guide,” updated 2026.
-
ESA / Webb, “Webb reveals dust and water surviving in the extreme environment around the Milky Way’s central black hole,” August 2026.
-
ABC News, “Astronomers discover new type of cosmic object, ‘black hole star’,” August 2026.
-
ESA Space Environment Report 2026, September 2026.
-
CGTN and Xinhua, reporting on Tiangong international cooperation and Shenzhou-23, 2026.
-
NASA Spinoff 2026 and ESA connectivity reports, 2026.
-
NASA / Frank White, “The Overview Effect,” NASA documentation and interviews.
Novara Lin
Senior Editor & Clean Beauty Analyst
Novara Lin is a clean beauty researcher and wellness editor dedicated to demystifying modern skincare and evidence-based living. With a background in formulation science and consumer health reporting, she specializes in analyzing complex ingredient profiles, evaluating product safety, and bridging the gap between clinical research and daily self-care routines. Her work focuses on helping readers cut through industry noise to build minimal, highly effective routines rooted in transparency and skin health. When she isn’t testing active formulations or auditing non-toxic household choices, Novara leads editorial strategy for NovaRa Pure.